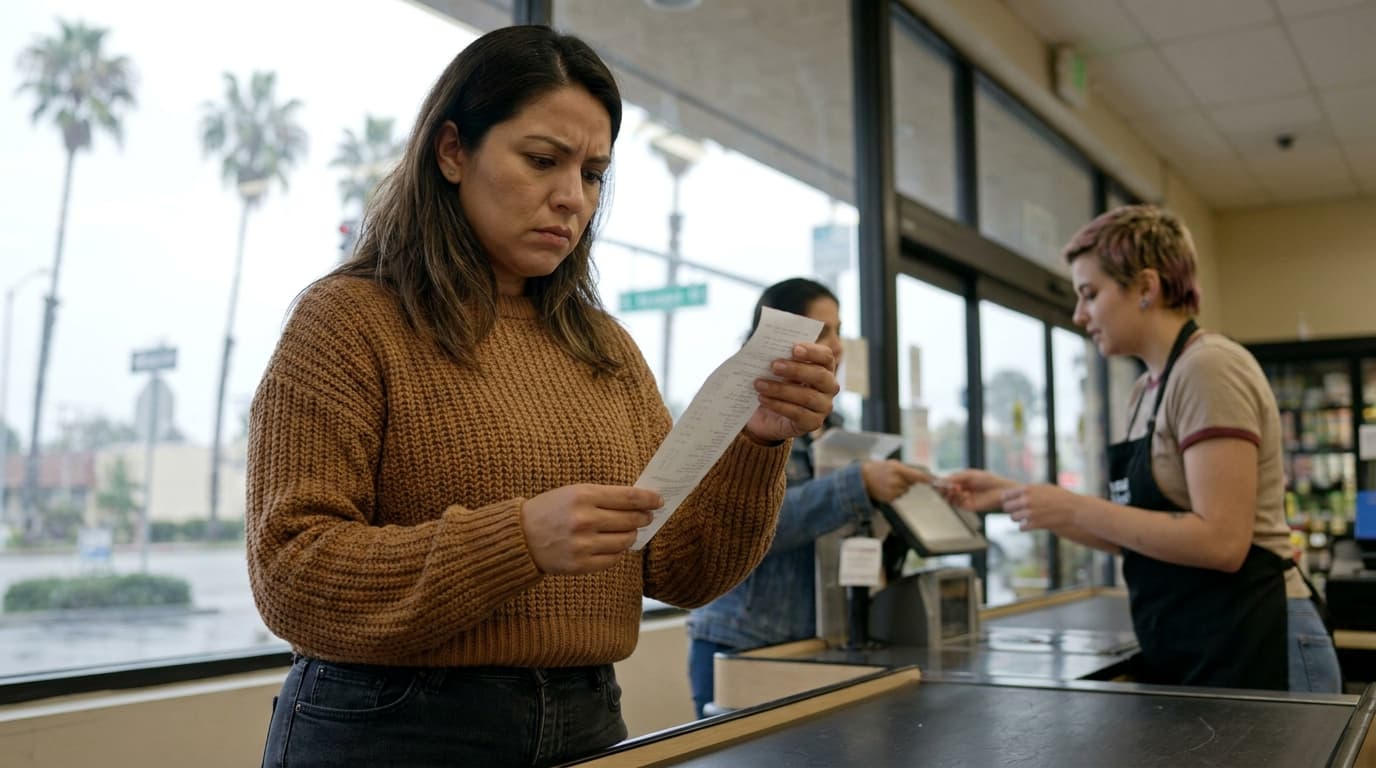
It started with a parking ticket. Then a dentist visit that insurance barely touched. Then the refrigerator died on a Wednesday night. By the time things settled down, she was carrying $14,000 across two credit cards, earning right around Los Angeles's median household income of $76,244 (U.S. Census Bureau, 2022 ACS), and watching her minimum payments barely dent the balance. Sound familiar? The cost of living in Los Angeles has a way of turning small setbacks into long-term debt.
Quick Answer
What is the cost of living in Los Angeles actually doing to everyday budgets in 2026?
The cost of living in Los Angeles is outpacing wages for many middle-income residents. Prices in the West region rose 3.2% over the past 12 months (Bureau of Labor Statistics, August 2026), and with the national consumer price index sitting at 334.980, LA tracks meaningfully above that baseline. Housing, gas, and groceries are the biggest pressure points. Read on for details on what it means for your specific budget.
What Does the Cost of Living in Los Angeles Actually Look Like in 2026?
Picture a Sunday grocery run in Silver Lake. Olive oil, chicken thighs, a bag of rice, a couple of avocados. You hand over $80 and wonder what happened to the $50 grocery run you remember from three years ago. That feeling is real and the data backs it up. The national Consumer Price Index (CPI) for all urban consumers hit 334.980 as of August 2026, according to the Bureau of Labor Statistics. That number tracks a basket of everyday goods including food, shelter, gas, and utilities, and LA's regional costs track above it.
Prices across the West region climbed 3.2% over the past 12 months (BLS, August 2026). With oil prices keeping gas elevated across Southern California, every commute and grocery trip chips away at take-home pay faster than most budgets can absorb.
How Much Does It Cost to Live in Los Angeles? A Neighborhood-by-Neighborhood Reality Check
Los Angeles is home to 3,881,041 people (U.S. Census Bureau, 2022 ACS) packed into a city where housing supply has never caught up with demand. That structural mismatch is why rent dominates every budget conversation here. A one-bedroom in Koreatown or Downtown LA might run $1,800 to $2,200 per month. The same apartment in Santa Monica or Brentwood can easily hit $3,200 or more. More affordable pockets like Glendale, Burbank, and the eastern neighborhoods offer slightly lower rents, but "lower" is relative when you're working with a median household income of $76,244.
Groceries have climbed steadily. Gas, tied to Brent crude prices that have stayed elevated above $100 per barrel through late 2026, hits Southern California commuters especially hard given that most residents depend on a car. Throw in utilities, childcare averaging well over $1,500 per month for a toddler, and internet, and a single person needs to clear roughly $65,000 to $70,000 a year just to stay above water without debt. A family of three needs significantly more.
Is the Job Market Keeping Up With Los Angeles Living Costs?
The national unemployment rate is 4.2% as of September 2026, according to the Bureau of Labor Statistics. On paper, that's stable. In practice, being employed in LA doesn't automatically mean financially secure. The city's economy runs on entertainment, tech, logistics, and hospitality, and those industries have wildly different pay floors. A grip on a film set and a software engineer at a streaming company are both "employed." Their financial realities are not the same.
Gig work is also deeply woven into how Angelenos earn. Rideshare, delivery, freelance creative work, all of it shows up as income but not as stability. Wages have grown, but the cost of living in Los Angeles has grown faster for renters and households without significant assets. That gap is where the debt starts.
Are High Interest Rates Making the LA Cost of Living Crisis Worse?
Yes, and here's the math on it. The average credit card interest rate at commercial banks is currently 21.19% (Federal Reserve Economic Data, FRED, August 2026). Carrying a balance means paying more than 21 cents in interest for every dollar you borrow. When rent takes half your paycheck and an unexpected car repair lands on a Tuesday, the credit card often becomes the solution. A $3,000 repair at 21.19% APR, paid off over 18 months, costs you a few hundred dollars more than the repair itself.
The 24-month personal loan rate at commercial banks sits at 11.9% (FRED, August 2026), which is meaningfully lower than carrying revolving credit card debt. Nationally, total revolving consumer credit outstanding hit $1,352,414 million (FRED, August 2026), which tells you that most Americans are using credit to manage living costs, not just big emergencies. You are not alone in this. For more on how rates are affecting everyday finances, see Rising Interest Rates & Cost of Living.
7 Signs the Cost of Living in Los Angeles Is Actually Crushing Your Budget
Signs 1–4: The Everyday Warnings Most People Ignore
- You're spending more than 35–40% of gross income on rent. Financial guidelines suggest keeping housing under 30%. At LA's rent levels against a $76,244 median income, many households are already past that threshold before groceries hit the cart.
- You're carrying a monthly credit card balance. At 21.19% APR (Federal Reserve, August 2026), even a $2,000 balance compounds fast. If you're not paying in full each month, it's worth calculating what that balance is actually costing you annually.
- You have less than one month of expenses saved. Most financial planners recommend three to six months. One month is the bare minimum. Nothing saved at all is a single unexpected expense away from debt.
- You're swapping grocery staples for cheaper alternatives just to hit your weekly budget. This isn't a lifestyle choice when it feels mandatory. It's a signal your income-to-expense ratio is too tight.
Signs 5–7: When It's Time to Take Action
- You're moving money between accounts the day before a bill hits. This juggling act is exhausting and it means your cash flow, not your habits, is the problem.
- One unexpected expense would put you into debt. A car repair. An ER copay. A rent increase letter. If any of those would require borrowing, your financial cushion is gone.
- You've used a personal loan or cash advance to cover recurring bills. That's a sign the math isn't working on a structural level. Refinancing high-interest debt into a lower-rate personal loan (11.9% vs. 21.19%, per FRED) is one concrete step. If you want to explore that route, Safe Bet Loans works with personal loan lenders who specialize in a range of financial situations, including those that traditional banks often decline.
What Are Los Angeles Residents Actually Doing to Manage Costs?
The most common move right now is geo-arbitrage within LA itself. Families are relocating to Burbank, Glendale, El Monte, or the Inland Empire to cut rent by $400 to $800 per month while keeping their city-based jobs. That's real money back in your pocket. Subscription and utility audits are another low-effort win. Most households are paying for two or three streaming services they rarely use, a gym membership from 2024, and an insurance policy they haven't shopped in three years.
On the debt side, consolidating high-interest credit card balances into a personal loan at a lower rate is a strategy worth examining. If you're carrying $10,000 at 21.19% APR and you can move that to 11.9% on a 24-month personal loan, the interest savings over the loan term are material. That's not magic, it's arithmetic. LA County's DCBA financial empowerment programs and 211 LA also offer free budgeting counseling for residents who want structured help. For perspective on how LA stacks up against other expensive cities, the Cost of Living Chicago comparison is a useful read.
Los Angeles vs. Other Major Cities: Is It Really That Much More Expensive?
Short answer: yes, in most categories. Using the national CPI of 334.980 (BLS, August 2026) as a baseline, LA's housing and transportation costs push well above average. Chicago has lower average rents in comparable neighborhoods and no state income tax burden at California's level, though Illinois has its own property tax challenges. New York City edges LA in transit costs and certain food categories, but LA's car dependency and gas prices (especially in an elevated oil price environment) add costs NYC residents don't carry the same way.
What LA offers in return is real: weather, a massive entertainment and tech job market, cultural diversity, and year-round outdoor access. Whether that value equation works for your life is personal. But the financial pressure is data-backed and it's not imaginary.
Frequently Asked Questions
What is the cost of living in Los Angeles in 2026?
The national CPI stands at 334.980 (BLS, August 2026) and LA tracks above it, with West region prices up 3.2% over the past year. Housing is the dominant expense. A single person realistically needs $65,000 to $70,000 annually to cover basics without accumulating debt, and families of three need considerably more.
How much do you need to earn to live comfortably in Los Angeles?
Most budget frameworks suggest $85,000 to $100,000 per year for a single person to live comfortably in LA without financial strain. The city's median household income is $76,244 (U.S. Census Bureau, 2022 ACS), meaning many residents are earning below what comfortable actually costs here.
What are the cheapest neighborhoods in Los Angeles?
Boyle Heights, El Sereno, Panorama City, Reseda, and Inglewood tend to have lower rents relative to the city median. Trade-offs vary by neighborhood, including commute distance and transit access. These areas are popular with residents doing intentional geo-arbitrage to reduce housing costs while keeping LA-based employment.
How are high interest rates affecting LA residents' budgets?
The average credit card rate is 21.19% (Federal Reserve, FRED, August 2026), and total U.S. revolving debt outstanding is $1,352,414 million (FRED, August 2026). For Angelenos already stretched by rent and gas, carrying any credit card balance compounds the pressure fast and makes escaping the paycheck-to-paycheck cycle harder.
Where can I get financial help if I'm struggling with LA's cost of living?
211 LA connects residents to local financial assistance programs. LA County's DCBA offers free financial empowerment counseling. Local credit unions often have better loan rates than commercial banks. If you're managing high-interest debt, we work with personal loan lenders who specialize in a range of financial situations, including those that traditional banks often decline.